Betaaljournaal 23
Newsletter Dutch Payments AssociationBack to school! I hope everyone had a nice summer vacation and could return to work with new inspiration and energy.
Thanks in part to the far-reaching harmonization of European payments in recent decades, our trips and vacations across borders have become notably easier. We can pay electronically everywhere, inside and outside the euro zone, with the Netherlands in the vanguard. Yet this harmonization continues apace. In this newsletter you can read about the EU plans for the follow-up to PSD2, with a new PSR regulation and a PSD3 directive. And with a legislation package for a digital euro; more on that in a future Betaaljournaal.
This harmonization relies heavily on digitization. This newsletter illustrates this with an update on easy travel in public transport with a contactless debit or credit card and on the state of e-commerce in the Netherlands.
Not everyone can keep up with the rapid pace of digitization. Still, it is important that as many as possible can handle their daily banking affairs autonomously and preferably digitally. Therefor we also provide the latest news on the pilot with bank information desks and the continuation of the Cash Covenant.
Enough stories to get you back in swing for the new payment season.
Gijs Boudewijn, managing director
- Amsterdam offers discount for traveling with debit or credit card
- Bank information desks: high satisfaction, few visitors
- Proposals from European Commission for PSD3 and PSR legislation
- Seven fallback options for card payment failures
- Additional agreements for Cash Covenant
- Berlin Group and nexo standards develop joint standards for digital euro payments
- Online purchases are stable, spending increases
- Agenda
Amsterdam offers discount for traveling with debit or credit card
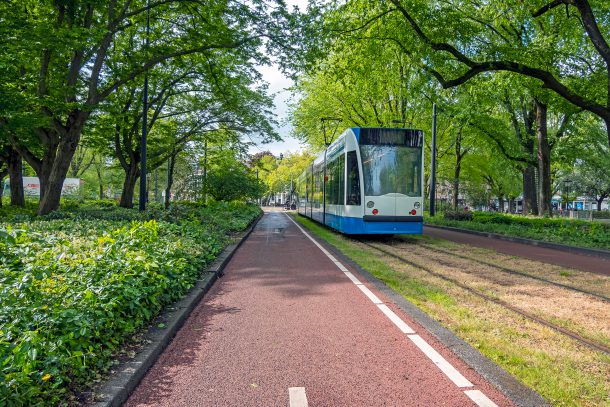
Amsterdam now offers a discount to frequent travelers who check in and out of public transport with a debit or credit card. Seniority discounts will follow later. To use a discount, a traveler must first register his or her payment card online with GVB in order to link the travel discount.
Until now, traveling with a debit or credit card was especially convenient for occasional public transport travelers and foreign visitors, as discounts were not yet available. Other carriers are expected to soon follow GVB’s example.
Even without discounts, checking in and out with debit and credit cards in urban public transport is rising fast. In The Hague, 10% to 15% of streetcar and bus journeys are now made with a payment card. In October 2022 The Hague was the first major city to introduce debit and credit card travel. In Amsterdam, over 12% of all journeys involve travelling with a payment card. In Rotterdam this was only introduced last June and already accounts for 6% of all journeys.
Bank information desks: high satisfaction, few visitors
In accordance with the commitment made by banks on January 30th 2023, we set up a pilot bank by June 1st with information desks in 10 municipalities, across 19 locations. This pilot ran until the end of August and featured variations in location type, staffing type (ranging from volunteers to professionals, both banking and non-banking) and site (city or village).
The pilot is now complete, except in a few places where staffing is still active. Research firm Perspective conducted an evaluation and presented the results to those directly involved, including the Accessible Banking working group, accessibility managers, libraries, Geldmaat and volunteers. All objectives were met, except for the target of 2 visitors per hour per desk on average. Both visitors and staff were highly satisfied.
The study produced several recommendations for the follow-up pilot, called ‘pilot 2.0’. Executives will decide on the follow-up in October. The locations for pilot 2.0 will be chosen in close cooperation with partners, including Alliantie Digitaal Samenleven, libraries and Geldmaat. The ultimate goal of pilot 2.0 is to collect sufficient data for a final decision on setting up permanent bank information desks. The full study report will be made available on the program website at the end of September.
Proposals from European Commission for PSD3 and PSR legislation
The European Commission has revised the PSD2 directive. After adjusting, adding or deleting certain provisions, they will reside in a regulation and a directive recently proposed on June 28:
- Proposal for a Regulation of the European Parliament and of the Council on payment services in the internal market and amending Regulation (EU) No 1093/2010 (‘PSR’) (incl. annex);
- Proposal for a Directive of the European Parliament and of the Council on payment services and electronic money services in the Internal Market amending Directive 98/26/EC, and repealing Directives 2015/2366/EU and 2009/110/EC (‘PSD3’) (incl. annex)
Notably, PSR is a regulation with direct effect, while PSD3 is a directive that must be transposed into the national legislation of each member state. With the proposals for PSR and PSD3, the European Commission has four main objectives:
- Better protection and more confidence for users of payment services.
- Further development of the ‘Open Banking’ framework.
- Better enforcement and uniform implementation of the legislation.
- Easier access for payment service providers to payment accounts and payment systems.
The Dutch Payments Association is currently working with members and the NVB on a joint response to these bills. We expect to submit this response on September 27th. The response focuses in particular on topics such as Open Banking, consumer protection, fraud detection, fraud data exchange, Confirmation of Payee (CoP) and Strong Customer Authentication (SCA), in addition to answers to requests for clarification from the industry. The Payments Association’s full response will be available on our website.
Seven fallback options for card payment failures
Thankfully, major card payment failures are extremely rare. Partly because the card payments infrastructure is so reliable, stores are often not well prepared if nevertheless a rare outage occurs. These are mostly limited interruptions, in a single store, in one neighborhood or with one telecom operator.
Fortunately, there are as many as seven different fallback options available to businesses in case of a temporary card payment failure, including iDEAL QR, mobile requests-to-pay, deferred card payments and, of course, cash. Our Geldland video (in Dutch), mentions all seven options.
On PIN.NL, we offer a simple interactive tool (in Dutch) that a business owner can use to select the most suitable fallback options, specifically for his or her business.
Additional agreements for Cash Covenant
With the Cash Covenant, the four major banks, Dutch Payments Association, cash service providers, De Nederlandsche Bank and representatives of consumers, the elderly, shopkeepers, the hospitality industry and gas stations, agreed on April 7th 2022 to ensure that cash remains readily available and usable. On June 12th, all parties agreed to continue the Covenant, including some small banks that have now also signed the Covenant. A few additional agreements have been included in an addendum to the Covenant; these are agreements proposed by DNB on indexing cash service fees.
Berlin Group and nexo standards develop joint standards for digital euro payments
Although the introduction of the digital euro is not yet certain, nexo standards and the Berlin Group are already joining forces on this topic. They will develop joint standards to facilitate digital euro payments throughout the EU. These standards will ensure seamless integration with existing payment infrastructures and contribute to ease of use. The Dutch Payments Association is a member of the Berlin Group and is actively involved in this initiative.
MORE ON THIS COOPERATION AND ON THE FUTURE OF A DIGITAL EURO
Online purchases are stable, spending increases
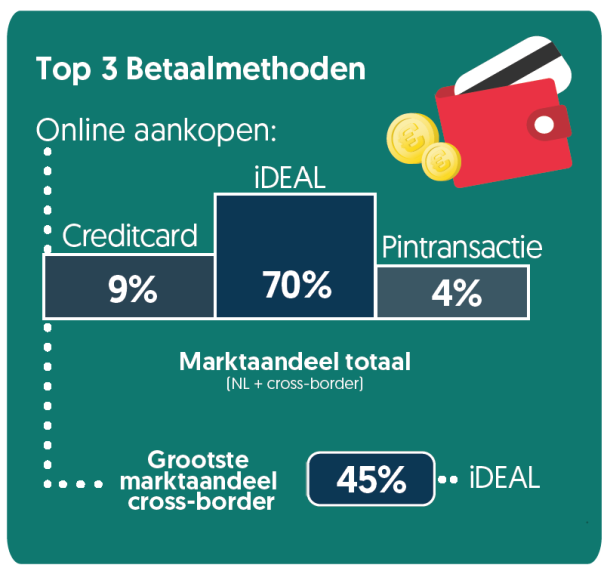
In Q1 of 2023, Dutch consumers spent over €8.5 billion online, a 5% growth compared to Q1 of 2022. Although the number of purchases remained stable at 84 million, the average amount per purchase rose to €102. For products, the increase in the DIY/Gardening category stood out in particular, while the Food/Nearfood category showed a decline.
The services sector in particular continues to grow, especially in the Tickets, Travel and Accommodations sectors.
VIEW ALL FACTS AND FIGURES FOR Q1 2023
Agenda
- October 2nd – Giro Stakeholder Forum / Card Forum
- October 12th – Shopping Today Event
- October – Board meeting
- October 18th & 19th – Open Banking Expo Londen
- November 15th – General Members’ Assembly and subsequent yearly conference of the Dutch Payments Association
- November 27th – Digital Inclusion Day
- November 28th – Maatschappelijk Overleg Betalingsverkeer
Member Bulletins
In addition to this Betaaljournaal, the Dutch Payments Association issues Member Bulletins. These bulletins usually appear a few times a month and relate to a specific topic. If you are a member and you do not yet receive these bulletins, you can subscribe to the mailing list via secretariaat@betaalvereniging.nl.
Subscribe to Betaaljournaal
For the latest developments in payments, stay informed via Betaaljournaal. You can register here: